
If we cast our minds back to March 2020, we were in the midst of one of the worst market drawdowns in history. It is hard to imagine that just nine months later we would report the JSE All Share Index ending the calendar year up by 7%. This positive return was not without volatility and extreme divergence between sectors and stocks.
If we look at general equity funds in South Africa, there was a 43.9% spread between the best and the worst-performing funds. The top performer, Fairtree Equity, reported a 19.8% return, while Nedgroup Investments Growth was the worst performer, declining by -24.1% for the year.
South African bonds, which has been a significant holding and area of high conviction for Morningstar, was the best performing domestic asset class for the year – despite downgrades to our sovereign credit rating and large outflows from foreigner investors.
Listed property had a very tough year, losing -34% in 2020, despite the rebound in the fourth quarter.
The 3% interest rate cut that came into effect in 2020 will impact money market and cash returns for investors going forward. Most investors have become comfortable with a 6% return from money market holdings, however, that number is set to almost halve in the coming year.
Globally, most markets, except for the FTSE 100 (the UK Market), ended the year in positive territory in US dollar terms. The most notable performance came from the tech-heavy Nasdaq 100, which increased by almost 50% for the year. The tech sector was a direct beneficiary of lockdown restrictions imposed globally due to the Covid-19 outbreak.
Global stocks, corporate bonds, real estate, gold, commodities, and even bitcoin have all moved higher and delivered positive performance.
The wave of “good news” comes with many fascinating and constructive sub-plots. One of the most interesting happened in the fourth quarter of 2020, where small-cap value stocks bucked a multi-year trend to join the winner’s list. This was partly marked by President-elect Biden’s victory (the so-called blue wave) but is also a vision for life after lockdowns – with the reopening of the economy considered a positive for economically sensitive and cyclical stocks.
Company defaults and bankruptcies also remain low globally, defying the doomsayers, supported by record stimulus and the cheapest borrowing rates ever seen.
Where to from here?
At the heart of Morningstar’s investment process is our valuation-driven asset allocation. This process continually seeks the most undervalued assets, and in turn, avoids what we consider to be expensive. We continue to search the investible universe for such opportunities and calibrate the possibilities on a risk-reward basis. We then build portfolios to express our best views to ensure that clients who remain invested will reap the benefits over the long term.
The current opportunity set is exciting. Even though markets rallied recently, one must remember that the performance within markets is incredibly divergent. For example, only a third of shares on the ALSI ended in positive territory for 2020.
Below is a high-level view of our asset class convictions and areas of the market where we are seeing opportunity:
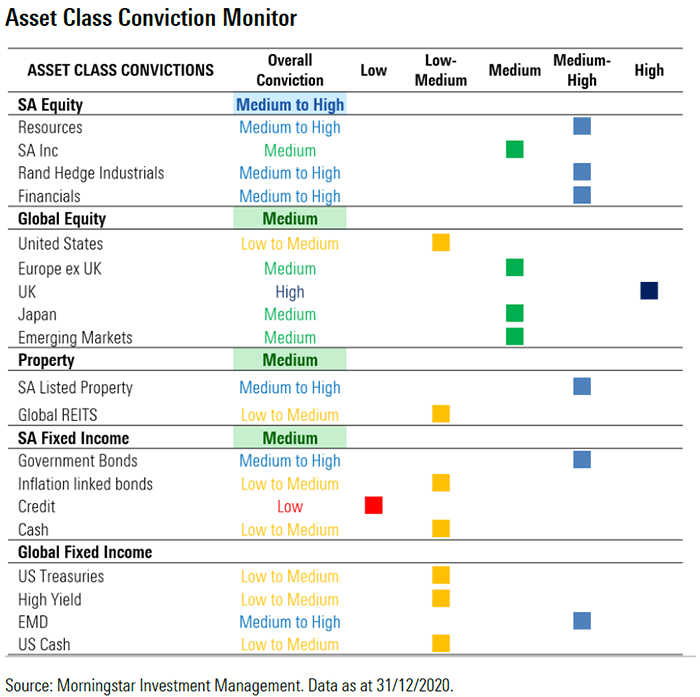
Within our domestic portfolios, we have reduced our cash allocations in favour of South African equities and South African bonds. While listed property is looking attractive on a valuation basis, we are cognizant of risk and therefore we currently have limited exposure to this asset class.
For our Regulation 28 compliant portfolios, we remain fully invested offshore. While we may be entering a period of possible rand strength, we believe that long term investors will benefit from not only the diversification that global exposure brings to portfolios, but more importantly, the investment opportunities we have accessed via our global exposure.
Conscious of the fact that the South African investment universe has shrunk meaningfully over the past decade and there is a limited subset of investable industries, we look at our global holdings and local holdings together to ensure that we have high conviction in all of the assets that we own, according to our capital markets valuation framework.
Within our global portfolios, we believe that US large-cap equities are currently overvalued; however, we see good investment opportunities in areas outside of the US, namely UK Equities, Emerging Market Equities (especially Korea and Mexico) and Japan. Within US equities, we do see value in certain sectors such as energy and financials.
Looking to the future, investors must consider the risks they can’t see or at least those they haven’t given weight to. Above all else, investors need to weigh the valuations they are paying, as we have seen extreme divergences that present both an opportunity and a risk. While we have exposure to areas of the market where we are seeing attractive opportunities, our portfolios remain defensively positioned and are constructed to ensure that risk is considered and there is a balanced exposure to both growth and income assets.
We remain confident that our positions are in the best interests of our clients – acknowledging tomorrow’s challenges and working towards a prosperous 2021 with good financial decision making.